Credit Card Debt Statute of Limitations: Complete State by State Guide
Unpaid credit card balances can create financial difficulties long after an account becomes delinquent. Collection agencies may continue requesting payments, creditors may transfer accounts to debt buyers, and borrowers may receive legal notices concerning outstanding balances. However, creditors do not have unlimited time to file lawsuits to recover unpaid credit card debt. Each U.S. state establishes a legal deadline known as the credit card debt statute of limitations.
This deadline determines how long a creditor or debt collector generally has to initiate legal action over an unpaid balance. The limitation period varies across the country, usually depending on state laws, the classification of the credit agreement, and the account's payment history.
In 2026, understanding these differences is especially important when dealing with older credit card accounts. This complete state-by-state guide explains the applicable legal frameworks, how limitation periods work, what happens when they expire, and the protections available to consumers.
What Is the Credit Card Debt Statute of Limitations?
The credit card debt statute of limitations is the legal time limit within which a creditor or debt collector can file a lawsuit to recover an unpaid credit card balance.
Every state has its own limitation laws. Credit card accounts are generally treated as open-ended accounts or contractual obligations because they allow borrowers to use available credit, repay balances, and borrow again.
Depending on the state, the limitation period for these obligations can range from two to ten years. Some states apply different deadlines to written contracts and open accounts, while others have specific provisions for consumer debt.
Once the applicable period expires, the debt generally becomes time-barred. Covered debt collectors cannot sue or threaten to sue consumers over time-barred debt under federal collection regulations.
However, an expired limitation period does not automatically eliminate the balance or remove it from a credit report. It primarily affects the legal remedies available to creditors and covered debt collectors.
Credit Card Debt Statute of Limitations by State in 2026
The limitation period differs across the United States. Some states have shorter deadlines for open accounts, while others apply the same general period to written and unwritten contractual obligations.
The following overview covers all 50 states and the District of Columbia. These are general statutory reference periods for consumer debt, not guaranteed deadlines for every credit card account. The applicable period may change depending on how a court classifies the credit agreement.
Credit Card Debt Statute of Limitations by State (Part 2)
The periods above are general statutory references, not a substitute for determining the limitation period on an individual credit card account. State courts may classify credit card agreements differently, and special consumer debt laws, borrowing statutes, and contractual provisions can affect the applicable deadline. The District of Columbia is included alongside the 50 states for reference.
When Does the Credit Card Debt Statute of Limitations Clock Start?
The starting date is essential when calculating the credit card debt statute of limitations. In many situations, the clock begins when the account becomes delinquent, but the exact rule depends on applicable state law.
Common events that may affect the calculation include:
1. First Missed Payment
The limitation period may begin when you miss a required credit card payment and the account becomes delinquent. The date of the original delinquency is also important for determining the credit reporting period.
2. Last Payment Date
Some states use the last payment date when calculating the limitation period. Reviewing previous statements and payment records can help establish the account's history.
3. Account Default
Certain credit card agreements contain acceleration clauses that allow creditors to demand the full outstanding balance after a qualifying default. Depending on state law, the acceleration date may affect when the legal clock begins.
4. Charge-Off Date
A charge-off occurs when a creditor classifies a seriously delinquent account as a loss for accounting purposes. Credit card accounts are generally charged off after approximately 180 days of missed payments. However, a charge-off does not automatically restart the limitation period or create a new deadline.
Can Making a Payment Restart the Statute of Limitations?
Yes, making a payment toward an old credit card balance can affect the limitation period in certain states.
Some states recognize partial payments or written acknowledgments as events that can restart or revive a creditor's ability to pursue legal action. Other states prohibit the revival of expired consumer debt.
For example, states such as Ohio and South Carolina have rules under which payments can affect the limitation period. New York, Maryland, and Washington provide stronger protections against reviving certain expired consumer debt claims.
The requirements vary significantly. Some states require a signed written acknowledgment, while others recognize voluntary payments.
Before making a payment, signing a repayment agreement, or acknowledging an old balance, check the applicable state law. A consumer debt attorney can help determine whether the proposed action could affect your legal position.
What Happens When the Statute of Limitations Expires?
When the applicable limitation period ends, the debt generally becomes time-barred. This affects the legal options available to creditors and debt collectors.
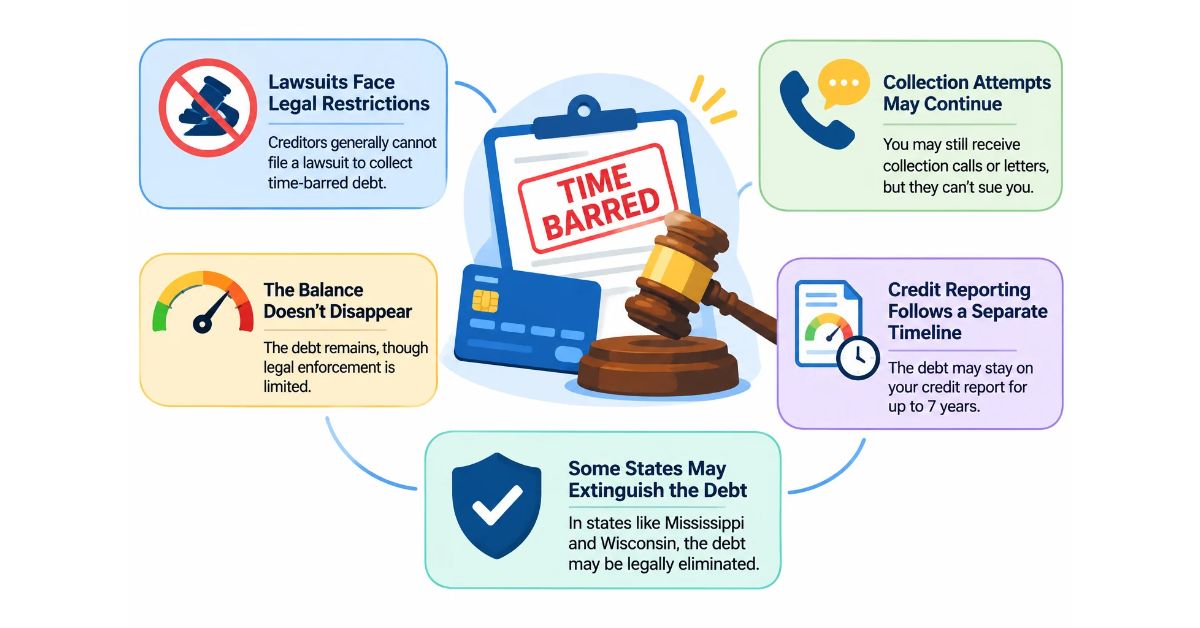 Here are some important consequences:
1. Lawsuits Over Time-Barred Debt Face Legal Restrictions
Under the Fair Debt Collection Practices Act (FDCPA) and Regulation F, covered debt collectors cannot bring or threaten legal action to collect time-barred debt.
However, the federal restriction generally applies to third-party debt collectors covered by the law. Original creditors may be subject to different rules, including additional state-level protections.
2. Collection Attempts May Continue
An expired limitation period does not necessarily prevent collectors from contacting consumers.
In many jurisdictions, collectors may still request voluntary payment on time-barred debt, provided their communication follows applicable federal and state laws.
3. You Must Respond to Court Notices
The statute of limitations generally works as an affirmative defense. This means consumers may need to raise it when responding to a lawsuit.
Ignoring a summons can result in a default judgment, even when the debt appears to be time-barred. Always follow the court's response deadline.
4. The Outstanding Balance Does Not Automatically Disappear
In most states, the expiration of the limitation period restricts legal enforcement rather than automatically eliminating the debt.
Mississippi and Wisconsin have specific laws that can extinguish the underlying right after the applicable period expires. Louisiana follows a different civil law framework for prescribed obligations.
5. Credit Reporting Follows a Separate Timeline
The Fair Credit Reporting Act (FCRA) generally allows most negative account information to remain on consumer credit reports for seven years, calculated under applicable reporting rules.
Therefore, an account may become time-barred while still appearing on your credit report.
How Does the FDCPA Protect Consumers From Debt Collection?
The Fair Debt Collection Practices Act is a federal law designed to protect consumers from abusive, deceptive, and unfair collection practices by covered debt collectors.
Some important protections include:
- Debt validation: Consumers can request information verifying the debt. A written dispute sent within the 30-day validation period generally requires the collector to pause collection of the disputed amount until verification is provided.
- Protection against harassment: Collectors cannot use prohibited threats, abusive language, or harassment to pressure consumers.
- Protection against time-barred lawsuits: Covered debt collectors cannot sue or threaten to sue over debts whose applicable limitation periods have expired.
- Dispute rights: Consumers can challenge inaccurate account information with collectors and credit reporting agencies.
- Communication rights: Consumers can request that collectors stop contacting them, subject to certain legally permitted communications.
If you believe a debt collector has violated your rights, you can submit a complaint to the Consumer Financial Protection Bureau (CFPB) or contact your state attorney general.
How to Handle Old Credit Card Debt
If you are dealing with an old credit card balance, taking a few precautions can help you understand your legal position.
1. Review Your Account History
Check previous statements, payment receipts, and collection notices. Identify the first missed payment and last payment date.
2. Request Debt Verification
Ask the collection agency for information about the original creditor, outstanding balance, and ownership of the account.
3. Check Your State's Laws
Determine the applicable limitation period and whether the account is classified as an open-ended account or written contract.
4. Avoid Uninformed Payments
Do not make partial payments or sign new repayment agreements without understanding their legal consequences.
5. Respond to Legal Notices
If you receive a court summons, do not ignore it. Review the applicable limitation period and seek legal assistance if necessary.
6. Explore Debt Management Options
If your credit card balances are difficult to manage, consider discussing repayment arrangements, debt management plans, or other available financial options with a qualified professional.
Understand Your Rights Under Credit Card Debt Laws
Understanding the credit card debt statute of limitations can help you determine how long creditors have to pursue legal action and what protections may be available when dealing with old credit card balances.
Although many states follow similar legal principles, their limitation periods, payment revival rules, and consumer protection provisions can differ considerably. An account that is time-barred under one state's laws may have a different legal status under another state's rules.
Before making payments or responding to collection requests, review your account history and identify the applicable legal deadline. If you receive a lawsuit or face complicated debt collection issues, consider consulting a qualified consumer debt attorney.
Knowing your rights can help you make informed financial decisions and handle old credit card debt with greater confidence.
Frequently Asked Questions
1. What is the average credit card debt statute of limitations in the United States?
Many states have limitation periods between three and six years for common consumer debt claims. However, some states allow longer periods. The exact deadline depends on the applicable state law and classification of the credit card agreement.
2. Can a credit card company sue me after seven years?
It depends on the applicable state law and account history. Seven years is generally associated with credit reporting rules, not the lawsuit limitation period. A debt may become time-barred earlier or remain legally actionable for longer.
3. Does credit card debt disappear after the statute of limitations expires?
No. In most states, the expiration of the limitation period does not eliminate the outstanding balance. It generally restricts the ability to pursue a lawsuit. Mississippi and Wisconsin have specific rules that can extinguish the underlying right.
4. Can a debt collector restart the limitation period?
A debt collector cannot automatically restart the clock by purchasing an account or contacting you. However, certain borrower actions, including partial payments and written acknowledgments, may affect the limitation period under some state laws.
5. Does moving to another state change the limitation period?
Moving does not automatically restart the clock. However, borrowing statutes, governing-law provisions, and other legal rules may determine which state's limitation period applies.
6. Can I dispute old credit card debt after the limitation period expires?
Yes. You can challenge inaccurate account information, request debt verification, and dispute incorrect credit reporting even after the limitation period expires.