How to Fight Medical Bills: 2026 Dispute Strategy Guide
A medical bill that arrives higher than expected doesn't have to be the final number. Studies consistently find that a large share of hospital bills contain at least one error, from duplicate charges to incorrect billing codes, and many patients are simply paying whatever amount shows up rather than questioning it.
Knowing how to fight medical bills means understanding your rights, the documents you need, and the specific steps that give you the best chance of lowering, correcting, or settling a balance before it damages your finances or your credit. For general guidance on your rights when dealing with billing or collections, the Consumer Financial Protection Bureau's debt collection resources are a helpful starting point.
In this guide, we'll walk through how to dispute errors, appeal insurance denials, apply for financial assistance, negotiate what you owe, and what to do if a medical bill has already gone to collections.
Quick Overview: How to Fight Medical Bills
The most effective way to fight a medical bill is to request an itemized statement and your insurer's Explanation of Benefits (EOB), compare them line by line for errors, dispute anything incorrect in writing, and then negotiate or apply for financial assistance on whatever balance remains valid.
Most successful outcomes come from acting within the first 180 days after a bill arrives, before it's sent to collections, since this window gives you the most leverage to dispute charges, appeal denials, and apply for hospital charity care.
Medical bills are also treated differently from other debt in several ways, including specific protections under the No Surprises Act and, in many states, more forgiving credit reporting rules, which makes it worth understanding the process before simply paying what's listed.
How to Fight Medical Bills: Step-by-Step Overview
Important: Continue paying any portion of the bill you're not disputing to avoid late fees, but you generally shouldn't pay disputed charges until the review is complete.
Why Should You Review Your Medical Bills?
Medical bills can contain mistakes that are difficult to recognize without checking the details. A hospital statement may include services you never received, duplicate entries, incorrect procedure codes, or charges that were already adjusted by your insurance company.
Even a small billing discrepancy can increase your final out-of-pocket expense.
Reviewing your statement gives you an opportunity to question charges before making payments or agreeing to a repayment arrangement. It also helps you understand which amounts are covered by insurance and which are your actual responsibility.
How to Fight Medical Bills: 7 Practical Steps
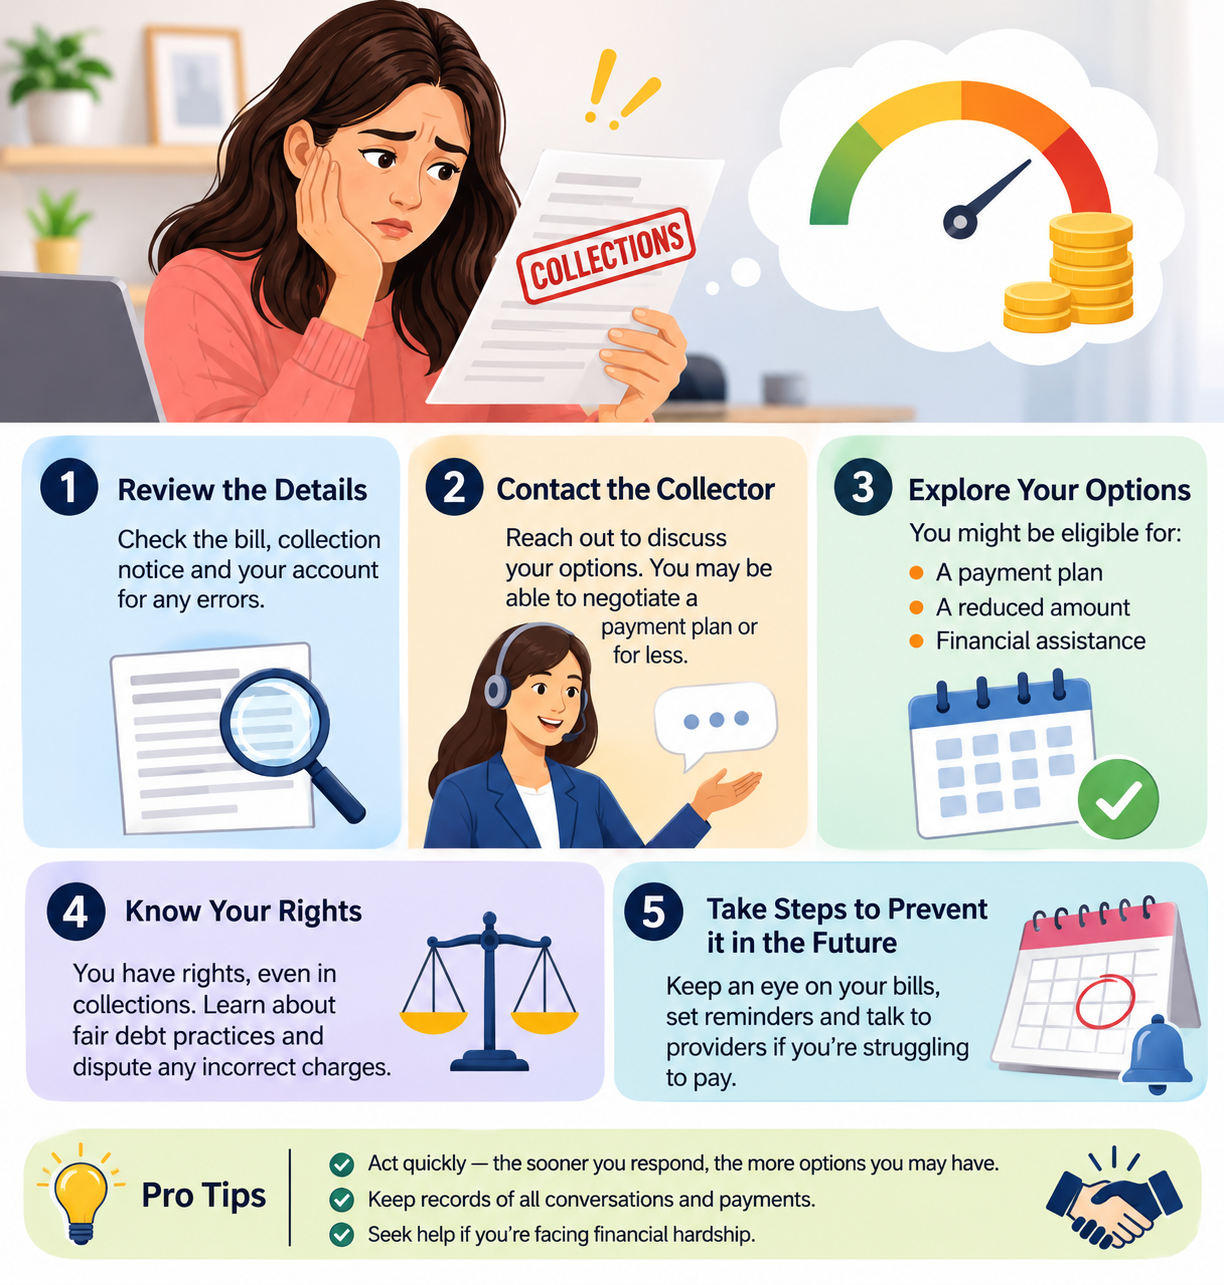
1. Request a Detailed, Itemized Medical Bill
Start by asking your hospital, clinic, or healthcare provider for an itemized bill.
Unlike a standard statement that displays a total balance, an itemized bill breaks down individual services, treatments, medications, procedures, and associated charges.
Check the statement for:
- Duplicate charges for the same treatment or service.
- Incorrect medication or procedure entries.
- Charges for cancelled appointments or tests.
- Services you never received.
- Unusually high quantities or unexplained fees.
- Incorrect patient or insurance information.
Ask the billing department to explain any charge you don't recognize. Keep a copy of the statement for reference during the dispute process.
2. Compare Your Bill With the Explanation of Benefits
If you have health insurance, request or download your Explanation of Benefits (EOB).
An EOB is a document from your insurance company explaining how a medical claim was processed. It generally includes the provider's charges, the amount covered by your plan, adjustments, and your estimated responsibility.
Compare the EOB with your hospital statement carefully.
Pay attention to:
- Whether the insurance company processed the claim correctly.
- Whether payments and contractual adjustments were applied.
- Whether your deductible or copayment was calculated correctly.
- Whether the provider billed you for an amount that should have been covered.
Remember that an EOB is not a bill. It explains how your insurer handled the claim. If the provider's statement doesn't match the EOB, contact both parties to clarify the difference.
3. Identify and Document Incorrect Charges
Once you have both documents, list every discrepancy you find.
Some common medical billing problems include:
Don't rely on a general complaint that your bill is too expensive. Identify the specific charge, explain why it appears incorrect, and attach supporting documents.
4. Submit a Written Medical Bill Dispute
After identifying errors, contact the provider's billing department and submit a written dispute.
Your letter should include:
- Your name and account or invoice number.
- The date of treatment.
- The specific charges you are challenging.
- A clear explanation of each discrepancy.
- Copies of your itemized bill and EOB, if applicable.
- Supporting documents or insurance correspondence.
Request a written explanation and ask the provider to place the disputed amount on hold while the issue is reviewed, if possible.
Send the letter through a trackable delivery method or use the provider's official dispute portal. Keep copies of all correspondence and payment records.
Important: There is no universal federal 30-day response deadline for every provider billing dispute. Ask the billing department for its review timeline and check whether your state has additional requirements.
5. Appeal an Insurance Claim Denial
Sometimes a medical bill becomes expensive because an insurance company rejects a claim or pays less than expected.
Before accepting the decision, review your Explanation of Benefits and the denial notice. The insurer should explain why the claim was rejected and provide instructions for challenging the decision.
Common reasons for insurance claim denials include:
- The insurer considers the treatment medically unnecessary.
- Prior authorization was missing.
- The service was classified as out-of-network.
- The claim contained incorrect information.
- The treatment wasn't covered under the policy.
You can generally request an internal appeal and, when eligible, an independent external review.
For many health plans covered by federal Affordable Care Act appeal rules, patients have up to 180 days after receiving a denial notice to request an internal appeal. However, deadlines and procedures can differ by plan and type of coverage, so check your denial letter.
If your internal appeal is unsuccessful, review the instructions for requesting an external review. For urgent medical situations, expedited review may be available.
6. Apply for Medical Financial Assistance or Charity Care
If you cannot afford your medical expenses, ask the hospital about its financial assistance policy.
Nonprofit hospitals are required to maintain financial assistance policies under federal tax rules. Eligible patients may receive reduced bills or, depending on the policy, have some or all qualifying expenses covered.
These programs are commonly known as:
- Charity care.
- Hospital financial assistance.
- Medical hardship assistance.
- Income-based payment assistance.
Eligibility requirements vary by hospital and may depend on household income, family size, financial circumstances, and the type of treatment received.
To apply:
- Visit the hospital's website and search for its financial assistance policy.
- Review the income and eligibility requirements.
- Complete the application and provide requested financial documents.
- Ask about application deadlines and processing times.
- Keep copies of your application and supporting records.
Some hospitals may also offer assistance even if they are not nonprofit organizations. Therefore, contact the billing department before assuming you don't qualify.
If your bill has already gone to collections, inform the collection agency that you are applying for financial assistance and request that collection activity be paused while your application is reviewed.
7. Negotiate Your Remaining Medical Bill
After correcting errors and exploring financial assistance, you may still have an outstanding balance.
You can contact the provider and ask whether it offers payment flexibility or a reduced balance.
Consider these options:
- Payment plans: Request smaller monthly installments that fit your budget.
- Prompt-payment reductions: Ask whether the provider offers a lower amount for paying the balance promptly.
- Hardship adjustments: Explain your financial circumstances and ask about additional reductions.
- Settlement arrangements: Ask whether the provider will accept an agreed amount to resolve the outstanding balance.
Before accepting an arrangement, request the terms in writing. Confirm the total amount, payment schedule, interest or fees, and what happens if you miss a payment.
What If the Bill Has Already Gone to Collections?
If a medical bill has moved to a collection agency, you still have options. Collectors typically purchase medical debt for a small fraction of its original value, which often leaves room to negotiate a reduced settlement. Under the Fair Debt Collection Practices Act, you generally have 30 days from first contact to dispute the debt and request validation before making any payment.
It's also worth knowing that under voluntary credit bureau rules, paid medical collections are generally removed from credit reports, and small balances are often excluded from reporting altogether, though rules continue to evolve and vary by state. If unpaid medical debt is already affecting your credit, our guide on medical debt removed from credit report walks through how that process works and what steps you can take.
When Medical Debt Is Part of a Bigger Financial Picture
Medical bills rarely arrive in isolation. If you're also managing IRS tax debt alongside medical expenses, understanding how to set up an IRS payment plan can help you avoid additional penalties while you work through medical billing disputes. Similarly, if a medical emergency led you to rely on short-term borrowing, our guide on how to get out of payday loan debt covers strategies for breaking that cycle without adding more high-interest debt on top of what you already owe.
Mistakes to Avoid When Fighting a Medical Bill
1. Paying Immediately Without Reviewing the Bill
Paying a bill in full before requesting an itemized statement removes your ability to catch errors that might have reduced what you actually owed.
2. Relying on Verbal Assurances
Phone calls with billing representatives can be helpful, but verbal promises aren't enforceable. Always follow up in writing and keep records of names, dates, and reference numbers.
3. Ignoring Appeal Deadlines
Insurance appeals and billing disputes often have strict windows, sometimes as short as 60 days. Missing a deadline can eliminate your ability to challenge a charge later.
4. Giving Up After the First "No"
Billing disputes frequently require multiple follow-ups before they're resolved. A denial or lack of response on the first attempt doesn't mean the dispute is over.
Conclusion
Fighting a medical bill starts with information: an itemized statement, your insurer's EOB, and a clear comparison between the two. From there, disputing errors, appealing denials, applying for financial assistance, and negotiating what remains can meaningfully reduce what you owe, often well before a bill ever reaches collections.
If medical debt is part of a larger financial challenge involving tax debt, payday loans, or credit reporting concerns, addressing each piece with the right strategy can make the overall burden more manageable. For further guidance on your rights, the Consumer Financial Protection Bureau offers free resources on medical billing and debt statue.
Frequently Asked Questions
1. How Can I Dispute a Medical Bill That Seems Too High?
Request an itemized statement and compare it with your insurance Explanation of Benefits. Identify duplicate charges, incorrect codes, or services you didn't receive. Submit a written dispute to the provider with supporting documents and request a review.
2. Can I Negotiate a Medical Bill After Insurance?
Yes. You can negotiate the remaining out-of-pocket balance after your insurer processes the claim. Ask about financial assistance, hardship reductions, prompt-payment arrangements, or manageable monthly payment plans.
3. Can a Hospital Send an Incorrect Medical Bill to Collections?
A provider may refer an unpaid balance to collections, but the amount must be valid and accurately represented. You can challenge incorrect charges with the provider and dispute a third-party collector's claim under applicable debt collection laws.
4. Does the No Surprises Act Protect Me From All Unexpected Medical Bills?
No. It protects patients from many qualifying out-of-network emergency and certain facility-based charges, along with certain air ambulance bills. Other out-of-network services may fall outside its protections.
5. How Long Do I Have to Dispute a Medical Bill?
There is no single deadline for every medical bill dispute. Insurance appeals, Good Faith Estimate disputes, collection disputes, and state-level billing complaints have different time limits. Check the relevant notice and applicable rules before submitting your dispute.